A hard rock lithium producer is buying its way into brine.
On August 31, Liontown Limited announced a binding farm-in agreement with NEXT Lithium Corp. that gives it a pathway to up to 100% of the Centenario lithium brine project in Salta Province, Argentina. Liontown operates the Kathleen Valley hard rock mine in Western Australia, so the deal is its first step beyond spodumene.
By lithium industry standards the upfront numbers are modest. The signal they send is bigger. An established producer has decided that brine, and the extraction technologies that make brine bankable, belong in its long-term portfolio.
For brine developers from Salta to Saskatchewan, that vote of confidence deserves a close reading.
A Staged Entry Built to Limit Risk
According to Liontown, the initial consideration is US$5 million in cash and US$10 million in Liontown shares, payable once the agreement becomes unconditional. The company can then spend up to US$40 million (about A$56 million) on project expenditure over four years. Mining Technology reports milestone payments of up to US$155 million over the same period, payable in cash, shares or a combination at NEXT Lithium’s election.
The farm-in runs in four phases. Canadian Mining Journal reports that a US$15 million work program over the first two years, including drilling targeted at transient electromagnetic survey anomalies, could earn Liontown an effective 49% stake. Liontown can walk away after phase one, two or three, but proceeding into phase three commits it to completing the full acquisition.
That structure matters.
It lets a producer buy knowledge before it buys a project. Each phase is gated by drilling results, so capital follows the geology rather than the market mood.
The Neighbours Make the Case
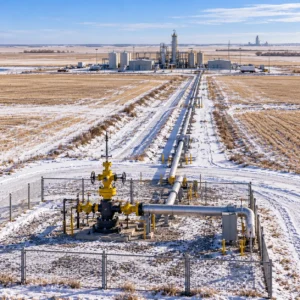
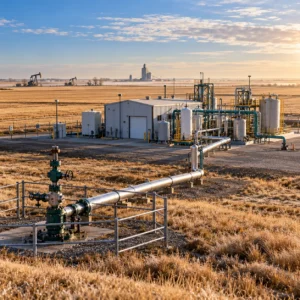
Location does much of the work here. According to Mining Technology, the 14,577 hectare property adjoins the Pozuelos-Pastos Grandes venture of Lithium Argentina and Ganfeng Lithium to the west and Eramet’s Centenario-Ratones operation to the south. Mining Technology says those neighbouring operations target approximately 150,000 tonnes a year of lithium carbonate production.
Centenario-Ratones is the most relevant reference point for direct lithium extraction. Eramet’s plant began operating on July 1, 2025, with 24,000 tonnes a year of lithium carbonate equivalent capacity. Adamas Intelligence describes it as the world’s first commercial-scale, greenfield, adsorption-type DLE plant without evaporation ponds outside China, and reports lithium recovery above 80%.
Exploring next door to a working DLE flowsheet is a very different proposition from exploring in isolation. The basin, the brine chemistry questions and the operating playbook are already being tested at industrial scale a short distance away.
Why Hard Rock Producers Are Looking at Brine
Liontown chief executive Tony Ottaviano put it plainly: “This transaction gives Liontown a low-cost entry into lithium brine.” The company describes the deal as opening a new growth frontier in lithium brine that complements its Western Australian operations.
The logic is portfolio balance. Spodumene and brine sit on different cost curves, reach the battery market through different conversion routes and behave differently through price cycles. Owning both gives a producer more than one way to grow.
Ottaviano was equally clear about why the partner matters, saying NEXT Lithium “knows lithium, knows brine, and knows Argentina” and describing that depth of expertise as exactly what Liontown wants alongside it.
Brine is not simply a different ore. It is a different discipline, closer to reservoir engineering and process chemistry than to open pit mining. Partnering with a brine specialist is how a hard rock company closes that capability gap quickly.
What It Means for Canadian Brine Developers
Developers in Alberta and Saskatchewan should take two lessons from the deal.
First, strategic capital is prepared to enter brine early when the structure fits. Liontown is committing to drilling, not to a finished feasibility study. Staged farm-ins with defined exit points give established producers a way in, and give juniors a way to fund resource work without giving away the whole project on day one.
Second, buyers of brine projects will increasingly judge them against operating DLE plants rather than pilot claims. Facilities such as Centenario-Ratones give the industry a benchmark for recovery and ramp-up, and projects in the Leduc and Duperow formations will be measured against that kind of evidence.
To stand out with strategic partners, Canadian developers will need to show:
- Reservoir data that supports long-life brine flow rates
- DLE performance on real brine over extended cycles
- A defined route to battery-grade carbonate or hydroxide
- Reinjection and water management plans regulators can approve
- Deal structures that let partners scale commitment with results
The Next Two Years Will Be Decided by the Drill Bit
The next milestone is straightforward. Liontown must deliver the first phase of drilling and decide whether the results justify moving toward the 49% threshold. Extraction technology, flowsheet design and any DLE selection come later and will depend on what the reservoir shows.
That sequencing is healthy.
Too many brine projects in the last cycle picked a technology story before they understood the resource. A disciplined, data-first entry by an experienced operator is the more durable model, and it is the kind of approach that tends to hold up when financing decisions arrive.
Hard rock built the first wave of lithium supply. The next wave is being drilled for in salt flats and deep brines, and producers have started buying their way in.